Applying for a loan can feel like a big step, particularly if you’re facing an unexpected expense and need a decision quickly. Knowing what happens after you submit your application can help you feel more confident about the process.
At QuidMarket, every application is assessed individually. Here’s a look at the loan approval process from start to finish.
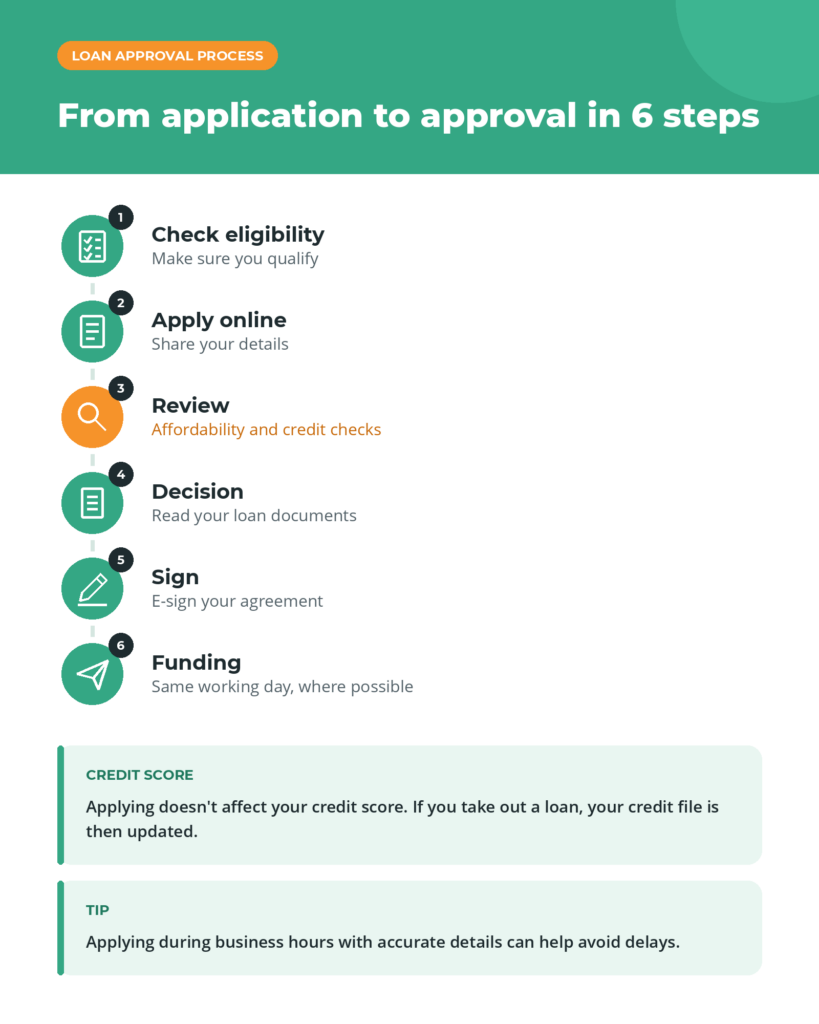
Step 1: Check you’re eligible
So, what are the steps to loan approval? Before starting an application, it’s important to make sure you meet the eligibility criteria first.
To apply, you must:
- Be between 18 and 67 years old
- Be a UK resident
- Have a valid UK mobile number
- Hold a UK bank account
- Be employed, either full-time or part-time
- Earn at least £1,250 take-home pay per month
Step 2: Complete your online application
What documents are required for loan approval? Well, once you’ve decided how much you’d like to borrow and selected a repayment term, you’ll be asked to provide information about yourself and your finances.
This typically includes:
- Personal details
- Employment information
- Income and expenditure details
- Bank account information
- Debit card details
You must ensure everything is accurate and up to date. The information you provide plays a key role in our affordability assessment and helps the team make a responsible lending decision.
Step 3: Your application is reviewed
One thing that sets us apart is our focus on making the application process both quick and straightforward, without compromising on responsible lending.
Our approach combines efficient processes with a thorough assessment of affordability, taking into account the information provided in each application alongside information held by credit reference agencies.
This helps us make informed lending decisions efficiently, while ensuring affordability remains at the heart of our approach.
Why affordability checks matter
Responsible lending is about more than simply deciding whether someone qualifies for credit.
Affordability checks help determine whether the repayments are realistic and manageable based on an applicant’s current financial circumstances. This helps reduce the risk of borrowing becoming difficult to repay later.
Step 4: Receiving a provisional decision
If your application progresses successfully through the initial review, you may receive a provisional approval. At this stage, you’ll be presented with several important documents, including:
- Pre-Contract Information
- Loan Agreement
- Adequate Explanations document
These documents contain important information about the loan, including the repayment schedule and the total amount you’ll be required to pay. Read these carefully and make sure you fully understand the agreement.
Step 5: Reviewing and signing your agreement
Once you’ve had the opportunity to review the documents and confirm you’re happy with the terms, you’ll be able to electronically sign the agreement.
We also send copies of the relevant documents to the email address provided during the application process so you can keep them for your records.
Taking a few extra moments to review everything at this stage can help ensure there are no surprises.
Step 6: Final approval and funding
After the agreement has been signed and the application finalised, the process moves to underwriting review.
If approved, we will transfer the funds on the same working day, where possible. Applications received outside normal business hours are processed as soon as possible on the next working day.
While many customers receive a decision quickly, the exact timing can vary depending on individual circumstances.
How long does a loan application take?
Several factors can influence how quickly an application moves from submission to funding:
- Applying during business hours – Applications submitted during business hours are often reviewed sooner than those submitted overnight or outside operating hours.
- Providing accurate information – We may, depending on your circumstances, ask for further information to support your application. Missing or inaccurate information may slow down the review process. Ensuring your application is completed accurately and any further information is provided promptly helps the team assess your circumstances more efficiently.
- Availability of supporting information – We review information from credit reference agencies alongside the details provided in your application. Access to this supports the assessment process.
- Bank processing times – After funds have been sent, transfer times can vary depending on banking processes and circumstances outside of our control.
Why do loan applications get rejected?
Having a loan application declined can be disappointing, especially if you were hoping to access funds quickly. However, as a responsible lender, we have to ensure that any borrowing we provide is suitable and affordable for the customer.
There are several common reasons why a loan application may not be approved:
- The loan is not considered affordable
- You don’t meet the eligibility criteria
- Information provided is incomplete or inaccurate
- Information held by a credit reference agency
- There has been a change in your financial circumstances
Explore your loan options with QuidMarket
That’s the loan application process explained. Ready to take the next step?
At QuidMarket, we offer short-term loans with repayment periods of three to six months. All applications are manually reviewed and assessed for affordability before a lending decision is made.
Find out more about how we work and whether a quick loan could help you manage an unexpected financial need. Apply online today.